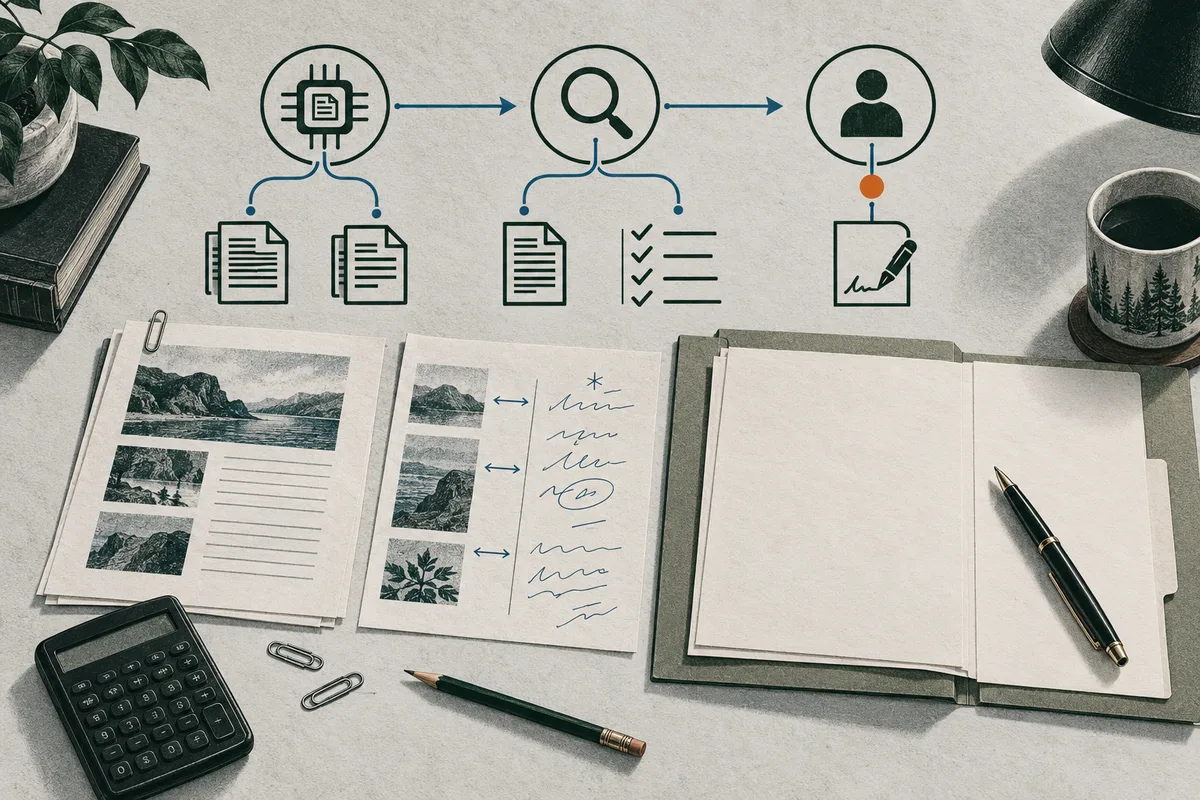
Treat an AI-generated tax research memo as a lead, not a client-file conclusion. For each material claim, authenticate its authority and pinpoint, confirm it applies to the issue and tax period, compare its conditions with documented client facts, check contrary authority and calculations, and record your disposition. The IRS OPR’s June 2026 guidance supports human review; this sequence is a practical method, not an IRS-prescribed form.
What should you check before an AI research memo informs a client file?
A U.S. tax preparer should treat an AI-generated research memo as a lead, not a client-file conclusion. For each material claim, ask four separate questions: Does the cited authority exist, and does its pinpoint support the statement? Is it effective for this tax period and issue? Do documented client facts meet the rule’s conditions? Have contrary authority and calculations been checked? A polished explanation or plausible citation cannot answer these questions. The IRS Office of Professional Responsibility’s June 2026 Introductory Guidelines for Responsible AI Use in Federal Tax Practice advises practitioners to review AI-created material and verify facts, citations, and calculations. Treasury Department Circular No. 230 sets diligence standards for practitioners and matters within its scope; covered written advice must consider relevant facts and relate law to facts. These sources support careful human review, but do not prescribe the proposition-by-proposition sequence used here. Record each claim as verified, corrected, unresolved, or discarded, and keep unresolved claims out of a settled conclusion. The memo can point toward research; the preparer must establish that each claim fits the authority, period, and client record.
Sources: Introductory Guidelines for Responsible AI Use in Federal Tax Practice; Treasury Department Circular No. 230
Why can a correct-looking answer still fail at the proposition level?
A tax research memo can look orderly and still leave its central conclusion unproved. A material proposition is a legal or factual assertion that could change the advice or return position. For each one, separate four questions: does the cited authority exist; does it support this exact sentence; does it apply to the issue and tax period; and do the documented client facts satisfy its conditions? A “yes” to the first cannot stand in for the others. A real citation may sit beside a claim it never establishes. A correct general rule may concern another year or issue. And a rule accurately summarized in the abstract may not fit facts the client file documents. This is citation laundering: an authentic source or polished bibliography lends an appearance of verification to neighboring claims that remain unchecked. The IRS Office of Professional Responsibility’s “Introductory Guidelines for Responsible AI Use in Federal Tax Practice” advises practitioners within Circular 230’s scope to review AI-created material and verify facts, citations, and calculations. That guidance supports scrutiny; the proposition-by-proposition release gate here is a practical method, not an IRS-prescribed form.
Generated research is usually read as a continuous explanation, while its support is not necessarily continuous. A paragraph may combine a rule, exception, date, assumed fact, and calculation. If the rule is sound but the date is wrong, the conclusion may change. If the rule and date are right but a condition is absent from the client record, the answer is still unestablished. If the source supports only a narrower statement, confident wording can outrun the authority. Focus on claims that could affect treatment: a governing requirement, exception, eligibility condition, filing-year threshold, or numerical result. Check the citation where each material proposition appears, not simply by finding a source somewhere in the bibliography.
A 2025 study, “Performance of LLMs on VITA test: potential for AI-assisted tax returns for low income taxpayers,” provides bounded evidence for task-level checking. Researchers compared six then-tested systems with expert-grounded answers to 130 IRS Volunteer Income Tax Assistance certification questions, also using syntactically altered versions for 390 question instances. Results varied by model and format. On open-ended questions requiring numerical calculation and tax-rule application, the strongest reported model scored 48.89% overall, or 22 of 45 questions. The paper calls these initial indicators and says further research is needed. These were VITA test questions, not professional research memos; the tested model versions do not establish current-system reliability or an error rate for any client file. The study does illustrate that performance on structured recognition and open-ended application differed. Fluency or a single confidence impression is therefore a poor substitute for checking the particular claim and task.
The useful unit of review is the proposition, not the memo’s tone. Mark claims that could alter the conclusion, then test source, scope, period, and factual fit separately. A citation’s existence locates a source; it does not prove the cited passage supports the sentence. Verified law does not supply client facts that were never established.
Sources: Performance of LLMs on VITA test: potential for AI-assisted tax returns for low income taxpayers; Introductory Guidelines for Responsible AI Use in Federal Tax Practice
What does the governing guidance require, and what does this method add?
Three layers matter when a preparer reviews generated research: Circular 230’s regulatory text, the IRS Office of Professional Responsibility’s interpretation for AI use, and a practical file procedure. The OPR bulletin explains its view of existing duties; this article’s proposition-by-proposition release gate is an editorial method, not an IRS-prescribed form. Keeping the layers distinct avoids attributing extra legal force to a suggested checklist.
Circular 230 §10.22 requires practitioners to exercise due diligence in preparing, assisting with, approving, or filing papers relating to IRS matters, and in determining the correctness of representations to Treasury or clients about IRS matters. It addresses reliance on another person’s work: due diligence is presumed when reasonable care is used in engaging, supervising, training, and evaluating that person, considering the relationship. The text does not mention generative systems. Checking one citation alone does not establish due care. These duties apply to practitioners and activities within Circular 230’s scope, not every person called a tax preparer in every engagement.
Section 10.37 sets standards for covered written advice on federal tax matters. It requires reasonable factual and legal assumptions, consideration of relevant circumstances, efforts to identify relevant facts, and relating applicable law and authorities to those facts. Reliance on representations is unreasonable when the practitioner knows or should know they are incorrect, incomplete, or inconsistent. Review applies a reasonable-practitioner standard considering engagement scope and the type and specificity of advice. A generated memo cannot supply missing client facts or connect law to facts actually established. Whether an internal note is covered advice depends on context.
The OPR’s June 24, 2026 bulletin, “Introductory Guidelines for Responsible AI Use in Federal Tax Practice,” says practitioners should thoroughly review AI-created documents before delivery or submission, including checking facts, citations, and calculations. It discusses competence, firm procedures, and data handling. This guidance interprets Circular 230; it is not a new regulation or accuracy study. Consult the provisions for underlying rules and the bulletin for OPR’s AI application. Neither prescribes this article’s workpaper fields.
The AICPA describes its Statements on Standards for Tax Services as enforceable tax-practice standards for its members. That scope differs from Circular 230. Its overview establishes whom the AICPA says the standards govern, not the detailed requirements of each standard; consult the relevant text. Membership, other professional requirements, firm policy, engagement terms, and advice type can affect which rules apply.
The practical method adds traceability. For each material proposition, record the authority and pinpoint checked, relevant period, client facts, assumptions or calculations, contrary authority considered, and disposition: verified, corrected, unresolved, or discarded. These proposed fields are not an IRS-required template. They show another reviewer what was checked and what remains open. The method makes one review path visible without claiming to exhaust governing duties.
Sources: Treasury Department Circular No. 230; Introductory Guidelines for Responsible AI Use in Federal Tax Practice; Statements on Standards for Tax Services
How do you authenticate each citation and read what it actually says?
Start with the proposition, not the bibliography. Break the generated memo into individual statements that could affect the analysis, then identify the source offered for each. For every material proposition, ask four questions: does the authority exist; does the pinpoint support the sentence; does the source establish the rule at the strength claimed; and can this source support this issue? A citation can pass the first check and fail the others. A polished list of authorities is only a set of leads until each item is opened and checked. Resolve the citation to an authoritative text. For statutes and regulations, use the official code or regulatory text; for IRS rulings, procedures, notices, and published guidance, locate the IRS publication; for a case, locate the opinion from a court or reliable legal repository. Match the pinpoint exactly: section and subsection, page, paragraph, or quoted passage. Read the surrounding text for definitions, exceptions, conditions, and cross-references that could change its meaning. Check that a quotation is exact and a paraphrase preserves the source’s limits. The IRS Office of Professional Responsibility’s *Introductory Guidelines for Responsible AI Use in Federal Tax Practice* advises practitioners to verify facts, citations, and calculations and says legal citations should be checked and cases read. That is guidance about review; it does not make a generated citation self-authenticating. For a case, verify the court, date, procedural posture, issue decided, and holding before relying on the memo’s characterization. A decision about a motion or particular record may not establish a broad rule for different facts. For any authority, separate what the text says from what the memo infers. *Treasury Department Circular No. 230* illustrates why the pinpoint matters: §10.37(a)(2) lists requirements for covered written federal-tax advice, including reasonable factual and legal assumptions, consideration of relevant facts, reasonable efforts to identify relevant facts, and relating applicable law and authorities to facts. A memo citing that provision for a wider claim should identify additional text that supports it; the citation alone cannot carry it. Read the regulation, not just a summary. Keep source types visible. A statute, regulation, published ruling, or court opinion differs from an IRS webpage, FAQ, professional commentary, or generated explanation. An explanatory page may help locate terminology or an authority, but it should not silently stand in for the source that controls the proposition. An official source also does not automatically support every claim attached to it: an IRS page may describe a process without deciding a distinct legal question. The OPR bulletin helps explain introductory IRS recommendations on AI review; Circular 230 supplies regulatory text for its provisions. Consider an example: a memo accurately names a regulation but says a paragraph establishes a broad rule, while the paragraph actually sets out a narrower condition. The citation exists, and the pinpoint may be correct, yet the sentence overstates what follows. Rewrite the proposition to match the text, locate further authority for the broader interpretation, or mark the point unresolved. Keep a proposition only when another reviewer can find its source and pinpoint and see support at the same level of certainty.
Sources: Treasury Department Circular No. 230; Introductory Guidelines for Responsible AI Use in Federal Tax Practice
How do you know the authority applies to the right tax period and issue?
Once a citation has been authenticated, ask whether it governs this question for this client’s tax period. A real source may still be outdated, out of jurisdiction, or changed. Keep those checks separate: authentication tests what a source says; applicability tests whether that source bears on the conclusion now being considered. Start with the period and jurisdiction. Identify the tax year, transaction date, filing date, and the legal question the client actually faces. Then check when the cited rule became effective and whether it applies to that period. For a regulation or statute, inspect the effective-date language and amendments; for administrative guidance, check its issue date, stated tax years, later updates, and any superseding notice or procedure. These checks do not give every source type an identical timeline. Next ask what weight the source can carry for this issue and forum. The text of a statute or regulation is different from an IRS webpage explaining a program; an FAQ or general page may orient research without resolving what controlling law requires. Their weight depends on the question, jurisdiction, and procedural posture; no one-line ranking resolves every tax question. Trace the proposition to the strongest relevant authority available, read any qualification or limitation, and note when the memo relies on explanatory material rather than the governing text. If state or local tax is involved, a federal source cannot settle that separate jurisdiction’s rule. The current IRS page, “Due diligence requirements for tax preparers,” illustrates why period and issue labels matter. It describes paid-preparer due diligence for specified claims, including EITC, CTC/ACTC/ODC and AOTC for returns from tax year 2016 onward; it also describes head-of-household and CTC/ODC requirements for tax years 2018 through 2025. Those dates and listed claims are the scope of that page’s summary, not a general rule for every research question or a substitute for checking applicable law and year-specific instructions. A memo citing this page for an unrelated deduction would need a different authority. Circular 230 is itself a useful reminder to check scope and date. The IRS PDF, “Treasury Department Circular No. 230,” is labeled revision 6-2014, so it should not be treated as proof that no later amendment exists. Its §§10.22 and 10.37 may be relevant to covered practitioners and activities, but the reviewer should confirm current text and applicability before relying on them. The IRS Office of Professional Responsibility’s June 24, 2026 “Introductory Guidelines for Responsible AI Use in Federal Tax Practice” discusses AI review through Circular 230. That bulletin is guidance about the regulation; its newer date does not itself turn every recommendation into an independently binding rule or make it the controlling authority for a client’s tax issue. As a practical workpaper step, record the tax period analyzed, jurisdiction, source version or date, and a checked-through date for later developments. If applicability remains uncertain, mark the proposition unresolved and research the specific gap before using it in a settled conclusion. A real, accurately quoted source is only the beginning: the preparer still has to establish that it governs this issue and period.
Sources: Treasury Department Circular No. 230; Due diligence requirements for tax preparers; Introductory Guidelines for Responsible AI Use in Federal Tax Practice
How do you test the rule against the actual client record?
Translate the verified rule into a fact test before applying it to the client. For each material element, identify the fact needed, what could establish it, what the file shows, and whether the conclusion follows. The chain is: rule element → fact needed → evidence in file → supported conclusion or gap. This keeps a legal proposition and its factual premise separate. A correct rule does not prove that the client meets it, and a plausible fact pattern in a generated memo is not evidence about this client. Label the basis of each important fact. A client statement is not the same as a contemporaneous document; a preparer’s inference is not a source fact; and a memo-supplied premise has no independent evidentiary value until checked. If evidence is incomplete, say what is missing. If sources disagree, preserve the inconsistency instead of selecting only the detail that makes the proposed answer work. The IRS page “Due diligence requirements for tax preparers” offers a useful but bounded comparison. For paid preparers determining eligibility for specified credits and filing statuses, it describes additional inquiries when information appears incorrect, inconsistent, or incomplete. It also lists records to retain for those claims, including relied-on client documents, notes about how, when, and from whom information was received, and records of extra questions and answers. The page says professional judgment is needed to assess whether information makes sense and whether follow-up resolves a concern. These practices show why a fact conclusion should be traceable to evidence and inquiry, not simply repeated from a research summary. That regime is not a universal AI-research checklist or recordkeeping rule for every tax issue. Its examples apply in specified contexts; keeping the same documents does not automatically satisfy other duties. Separately, Circular 230 §10.37, in “Treasury Department Circular No. 230,” addresses covered written federal-tax advice, including reasonable factual and legal assumptions, efforts to identify relevant facts, and relating law to facts. The IRS Office of Professional Responsibility’s “Introductory Guidelines for Responsible AI Use in Federal Tax Practice” says practitioners should verify AI-created facts and thoroughly review documents. These sources support careful fact work within their scopes; neither supplies a universal form for this proposed record. Consider an example: a memo’s eligibility analysis depends on a household fact for the relevant period. Identify the rule’s precise condition, locate what the client provided, compare it with relevant records in the file, and ask a focused follow-up question if evidence conflicts or leaves the condition unclear. Record the answer and its source, or mark the element unresolved. Eligibility does not follow merely because the memo states its premise confidently. Keep the conclusion proportional to what the file establishes. A missing document may call for requesting it; conflicting information may require clarification; an unresolved material fact means the analysis remains conditional. The question is whether each required fact has a defensible path from evidence to conclusion.
Sources: Due diligence requirements for tax preparers; Treasury Department Circular No. 230; Introductory Guidelines for Responsible AI Use in Federal Tax Practice
What contrary authority, assumptions, and calculations need a second pass?
A conclusion is not well tested until you have looked for material that could qualify it and checked the numbers independently. Search for authority that states the rule, but also for exceptions, qualifications, later developments, and decisions reaching a different result on relevant facts. Search by the rule, exception, and factual condition at issue, and inspect relevant official materials and case law rather than relying only on the memo’s query wording. Then compare dates, jurisdictions, procedural settings, and factual conditions before deciding whether a conflict is genuine. The generated memo's sources are a starting list, not the boundary of the research.
Keep assumptions visible while doing that comparison. Treasury Department Circular No. 230, §10.37, says covered written federal tax advice must rest on reasonable factual and legal assumptions, reasonably consider relevant facts and circumstances, use reasonable efforts to identify relevant facts, and relate applicable law and authorities to facts. It also says reliance on representations is unreasonable when the practitioner knows or should know an underlying representation or assumption is incorrect, incomplete, or inconsistent. In practice, write down which assumptions affect the conclusion and whether each is supported, still open, or contradicted. If the conclusion depends on an assumption that cannot be verified, qualify the advice or resolve the gap rather than silently treating the assumption as established.
Then redo every material computation from inputs you have verified. Recheck that source data belongs to the correct period and client, then verify the applicable threshold or formula, each arithmetic step, allocations, units, and rounding. The IRS Office of Professional Responsibility's Introductory Guidelines for Responsible AI Use in Federal Tax Practice specifically calls for verifying facts, citations, and calculations produced by AI, and says human scrutiny is essential. A correct citation does not validate a generated calculation, just as correct arithmetic cannot establish that the chosen legal rule applies.
A 2025 study, Performance of LLMs on VITA test: potential for AI-assisted tax returns for low income taxpayers, tested six older language models on 130 VITA certification questions and syntactically perturbed versions. It reported marked variation by model and question format; open-ended questions requiring numerical calculation and tax-rule application were difficult, with even its top model reaching 54.55% in the strongest reported open-ended category. It supports checking the actual computation, not assuming that every output is wrong or assigning a probability to this case.
For each competing item, record a short disposition such as supports, distinguishes, conflicts, or unresolved. Note the source’s date and legal weight, and why its reasoning matters or why its facts, period, or authority do not control the present issue. If a conflict or calculation remains material and unresolved, narrow the conclusion, continue direct research, or ask an appropriate reviewer before relying on it.
Sources: Treasury Department Circular No. 230; Introductory Guidelines for Responsible AI Use in Federal Tax Practice; Performance of LLMs on VITA test: potential for AI-assisted tax returns for low income taxpayers
How much review is enough for a material tax proposition?
Use the same basic gates for every material proposition: find and read the cited authority, confirm its date and scope, compare its requirements with documented client facts, check material contrary authority, and independently verify consequential calculations. Then deepen research according to unresolved questions and consequences, not a made-up risk score. A routine-looking issue still needs these checks; “routine” does not establish that a summary is right.
There is an efficiency case for using a tool to organize research leads or draft a first synthesis. The IRS Office of Professional Responsibility's *Introductory Guidelines for Responsible AI Use in Federal Tax Practice* recognizes potential streamlining and research benefits, but gives no measured time-saving estimate or comparison with direct review. It advises practitioners within Circular 230's scope to review AI-created material and verify facts, citations, and calculations. That supports human responsibility for the result, without showing every use is unsafe or prescribing a number of review minutes.
The 2025 study *Performance of LLMs on VITA test: potential for AI-assisted tax returns for low income taxpayers* tested six models against expert-agreed answers to 130 U.S. Volunteer Income Tax Assistance certification questions and two syntactic variants each, totaling 390 instances. Performance varied by model and format; all models struggled with open-ended tax-rule application and calculation. These were certification questions, not professional memos, and the tested systems were older. The results are no current error rate for your tool, but show why verification should match the task.
A focused review may close a straightforward issue when the primary source is clear, the period confirmed, facts documented, and no material conflict or calculation remains. Broaden research or ask an experienced reviewer when authority is ambiguous, facts missing, the issue novel or time-sensitive, calculations consequential, or contrary authority may change the analysis. Circular 230 §10.37 says covered written advice must use reasonable factual and legal assumptions, consider relevant circumstances, ascertain facts, and relate law to facts. It does not prescribe this review ladder; it explains why gaps matter.
Scale the second pass, not the floor. Source access, firm policy, the preparer's competence, issue, and data can change appropriate depth. If a material proposition still depends on an unchecked assumption or unresolved authority, mark it unresolved and research or escalate before relying on the conclusion. No sequence guarantees correctness, but visible proof gaps identify the next step.
Sources: Introductory Guidelines for Responsible AI Use in Federal Tax Practice; Performance of LLMs on VITA test: potential for AI-assisted tax returns for low income taxpayers; Treasury Department Circular No. 230
What must be recorded, and where does data security fit?
Keep a concise record that lets another reviewer trace your own reasoning, For each material proposition, note the issue and tax period, the exact proposition considered, the authority you opened and its pinpoint, when you checked whether it remained applicable, the client facts and records relied on, any calculation or assumption, contrary authority considered, your disposition, the reviewer and any open question. This proposition log is a practical editorial method; it is not an IRS-prescribed form. It makes the evidence path and your decision visible to another preparer.
The IRS page “Due diligence requirements for tax preparers.” For paid preparers and specified claims, it describes three-year retention of Form 8867, worksheets for listed credits, client documents relied on, notes about how, when, and from whom information was received, and records of follow-up questions and answers. It also says preparers must make additional inquiries when information appears incorrect, inconsistent, or incomplete. These rules cover defined due-diligence contexts; they do not establish a universal AI-research log requirement. Where an issue-specific rule requires records or follow-up, preserve what it calls for. A proposition log cannot by itself establish compliance with every applicable rule.
Make data permission a separate gate before entering any taxpayer information into a tool. Check firm policy and the applicable legal and professional restrictions, then confirm that the particular workflow is approved for the information involved. Check what the tool receives, its terms and settings, who can access inputs, how they are retained, and whether the firm's security plan permits that specific use. A product label or general firm approval may not answer whether this workflow is suitable for these data. Minimize the information shared, but do not assume removing a name makes a prompt safe: combinations of facts can still identify a client, and de-identification alone does not settle whether disclosure is allowed. If permission is unclear, keep identifiable details out and ask the responsible person under firm procedure.
The IRS’s “Publication 4557, Safeguarding Taxpayer Data” provides general security context for tax practices. It says protecting taxpayer data is required and discusses written security plans, limiting access to people who need it, encryption, and audit logs that record who acted, when, and what changed. It does not approve or certify a particular AI service, so cite it for the need for safeguards, not as proof that a given vendor or setting is suitable. The IRS Office of Professional Responsibility’s “Introductory Guidelines for Responsible AI Use in Federal Tax Practice” separately addresses AI use and urges practitioners to review generated work. Together, these sources support two controls: examine research before relying on it, and authorize data flow before prompting. Strong citation checking cannot cure an impermissible transfer of client information; equally, an approved tool does not make its research conclusions reliable. Record the preparer's reasoning and follow the safeguards and rules that apply to the engagement.
Sources: Due diligence requirements for tax preparers; Publication 4557, Safeguarding Taxpayer Data; Introductory Guidelines for Responsible AI Use in Federal Tax Practice
What is the next action when a check fails?
When a check fails, stop treating the proposition as settled. Mark it corrected if the source or application can be fixed, unresolved if evidence or interpretation remains open, or unsupported if the authority does not carry the claim. Leave unsupported language out of the conclusion, however polished the memo sounds. Choose a consequential proposition and follow its proof path: open the authority, read the relevant text in context, and verify its effective period and fit to the issue. Compare the rule’s conditions with facts documented in the client file. If a needed fact is missing or inconsistent, request clarification or records. Rebuild calculations from verified inputs. If contrary authority changes the analysis, record the conflict rather than conceal it. Circular No. 230 describes diligence and written-advice standards for covered practitioners. The IRS Office of Professional Responsibility’s “Introductory Guidelines for Responsible AI Use in Federal Tax Practice” applies that discussion to generated work and emphasizes human review. Neither makes this sequence a guarantee. A consequential ambiguity, unresolved conflict, or question outside your competence calls for direct research or escalation under firm procedure. Record the source checked, your disposition, and what remains open. The endpoint is a defensible path from authority through facts to the preparer’s conclusion. Until that path holds, the memo remains a lead, not a file-ready answer.
Sources: Treasury Department Circular No. 230; Introductory Guidelines for Responsible AI Use in Federal Tax Practice
Questions readers ask
Does the IRS require this exact proposition log?
No. It is a practical editorial method, not an IRS-prescribed form. Specific recordkeeping duties apply in defined contexts, and other requirements may depend on the engagement and applicable rules.
Does finding a real citation verify an AI-generated conclusion?
No. The source must support the exact proposition, apply to the issue and period, and fit the documented client facts. Check material contrary authority and calculations as well.
Can a preparer enter client information into any AI tool after removing names?
Do not assume so. Check applicable restrictions, firm policy, the specific workflow, and its data handling. Removing a name alone does not establish that disclosure is permitted.
What should a preparer do when a material check remains unresolved?
Keep the proposition out of a settled conclusion. Research the gap directly, obtain missing client information where appropriate, or escalate under firm procedure, then record the resolution.
Sources and notes
- Introductory Guidelines for Responsible AI Use in Federal Tax Practice
Supports the description of OPR guidance on reviewing AI-created work and checking facts, citations, calculations, and data handling.
- Treasury Department Circular No. 230
Supports the account of Circular 230 §§10.22 and 10.37 within their scope, including diligence and standards for covered written tax advice.
- Performance of LLMs on VITA test: potential for AI-assisted tax returns for low income taxpayers
Supports bounded discussion of a 2025 benchmark using VITA certification questions, with performance varying by model and question format.
- Statements on Standards for Tax Services
Supports the AICPA overview's stated member scope and the revised standards' effective date and subject areas.
- Due diligence requirements for tax preparers
Supports the specified due-diligence inquiry and recordkeeping examples, not a universal AI research documentation rule.
- Publication 4557, Safeguarding Taxpayer Data
Supports general taxpayer-data safeguard context, including security plans and access controls; it does not certify a particular AI service.
Apply this to your own work
See the whole job market at once.
Explore which occupations AI may reshape, then turn the signal into a practical response.
Explore the job map